|
The Week Ahead: Highlights
Asia-Pacific Preview
Inflation Reports Key for India Rate Expectations
By Brian Jackson, Econoday Economist
Indian inflation data for October will be published in the
week ahead and may shape expectations for the Reserve Bank of India policy
meeting early next month. At the RBIs last meeting in early October, officials
hiked rates by 25 basis points, the first increase since 2023, noting the
impact on the inflation outlook of the Iran conflict and adverse rainfall
patterns in the current monsoon season. Officials also revised up their annual
headline and core inflation forecasts for the current fiscal year from 5.0
percent to 5.2 percent and from 4.3 percent to 4.4 percent respectively.
September inflation data for India were published just after the October
meeting and showed a further increase in headline inflation to 5.54 percent
from 4.82 percent in August. This took inflation to its highest level since
October 2024 and close to the top of the Reserve Bank of India's target range
of two percent to six percent. The RBI has changed its policy stance from
neutral" to one of "calibrated tightening and strong inflation
numbers in the week ahead will strengthen the case for another rate hike next
month.
Chinese inflation data for October are also scheduled for release. Headline CPI
inflation in China increased further in September but core inflation was
steady, while producer price inflation increased to its highest level in more
than four years. This strength in producer prices largely reflects renewed
pressure on prices for fuel and raw materials associated with the Iran
conflict. PMI survey data published this week showed stronger some
moderation in input costs in the Chinese manufacturing sector in October.
China and Taiwan will publish October trade data in the week ahead after
September data showed strong growth in both imports and exports. South Korea
has already reported October trade data, with AI-related demand again boosting
headline numbers. PMI surveys have also generally shown solid growth in new
export orders across the region in October.
Monthly business and consumer sentiment surveys for Australia next week should
provide an updated indication of the response to recent policy decisions by the
Reserve Bank of Australia. The RBA has not increased policy rats five times
this year, including at each of its previous two meetings. Officials noted this
week that this policy tightening has tightened financial conditions and that
the economy is slowing. Next weeks surveys should show this is having some
impact on both current conditions and confidence about the outlook.
US Preview
CPI, PPI Reports in Focus in Light Week Ahead
By Theresa Sheehan, Econoday Economist
The week beginning November 9 presents a light data calendar
with a federal holiday on Wednesday to observe Veterans Day. US bond and stock
markets will have a full close. However, many non-government businesses will be
open with some of those offering a paid holiday on November 27 instead to make
a four-day weekend for Thanksgiving.
The light data calendar does not mean there are no important
reports. After the October employment report released on November 5, the focus
of markets will shift to the October inflation data. With the labor market
continuing to add jobs at a modest underlying pace consistent with maximum
employment in the current economy, the FOMC will have room to evaluate the
risks to price stability.
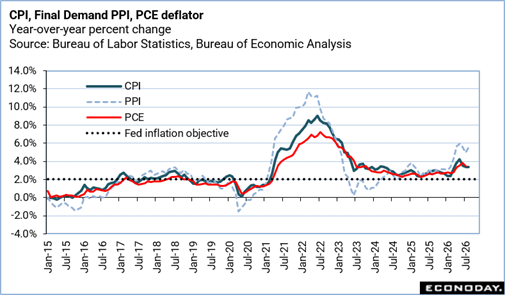
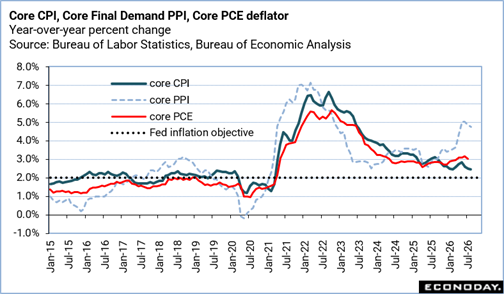
The consumer price index (CPI is set for release on Tuesday
at 8:30 ET and the final-demand producer price index (PPI) will be reported on
Friday at 8:30 ET. These are the final CPI and PPI reports that the FOMC will
have when the committee next meets on December 8-9 and are unlikely to suggest
that the current inflation pressures brought on by the start of the war on Iran
at the end of February have abated.
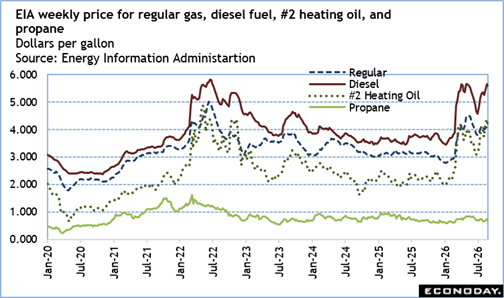
The outlook for the CPI and PPI data remains fundamentally a
story of energy costs with prior surges in oil prices rapidly filtering into
the costs for motor fuels and those lingering. Consumers and businesses felt
the immediate impact and there was no relief from ongoing elevated prices.
Household budgets remained pinched by prices at the pump and now costs for home
heating are higher as the colder months arrive. Businesses have little choice
but to try to absorb costs where possible but also pass on costs where not. The
reports are unlikely to sway Fed policymakers from their current bias toward
higher rates at the next meeting.
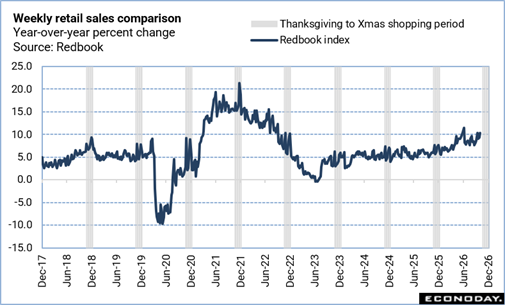
The Veterans Day holiday is often used by retailers to help
jumpstart spending for the winter holidays with so-called Black Friday deals
that are well before the traditional day after Thanksgiving. Some measures of
consumer spending in recent months look robust on the surface, but this may be
more due to higher prices than fundamentally stronger spending.
The Week Ahead: Econoday Consensus Forecasts
Monday
China CPI for October (Mon 0930 CET; Mon 0130 GMT; Sun
2030 EST)
Consensus Forecast, Y/Y: 0.8%
Consensus Range, Y/Y: 0.8% to 0.9%
Annual CPI inflation expected to recede to 0.8 percent in
October from 0.9 percent in September as demand remains sluggish.
China PPI for October (Mon 0930 CET; Mon 0130 GMT; Sun
2030 EST)
Consensus Forecast, Y/Y: 5.3%
Consensus Range, Y/Y: 5.2% to 5.4%
Rising energy and other commodities seen raising wholesale
price inflation to 5.3 percent in October from 5.0 percent in September.
Germany Merchandise Trade for September (Mon 0800
CET; Mon 0700 GMT; Mon 0200 EST)
Consensus Forecast, Balance: E18.1 B
Consensus Range, Balance: E15.6 B to E20.0 B
The surplus is expected to narrow to E18.1 billion in
September from E19.5 billion in August as the German export engine slows.
US Wholesale Inventories (Preliminary) for September (Mon
1000 EST; Mon 1500 GMT)
Consensus Forecast, M/M: 0.6%
Consensus Range, M/M: 0.5% to 0.6%
The consensus looks for no revision from the flash at an
increase of 0.6 percent on month.
Tuesday
Japan Household Spending for September (Tue 0830 JST;
Mon 2330 GMT; Mon 1830 EST)
Consensus Forecast, M/M: 0.3%
Consensus Range, M/M: -0.4% to 1.5%
Consensus Forecast, Y/Y: -3.6%
Consensus Range, Y/Y: -4.2% to -1.5%
China Merchandise Trade for October (ANYTIME)
Consensus Forecast, Balance of Trade: $127.0 B
Consensus Range, Balance of Trade: $125.9 B to $135.0
B
Consensus Forecast, Imports - Y/Y: 34.5%
Consensus Range, Imports - Y/Y: 30.3% to 37.3%
Consensus Forecast, Exports - Y/Y: 37.9%
Consensus Range, Exports - Y/Y: 28.1% to 40.7%
The trade surplus is expected at $127.0 billion in October,
reflecting surging exports and imports, but down from $133.5 billion in
September.
France ILO Unemployment Rate for Third Quarter (Tue 0730
CET; Tue 0630 GMT; Tue 0130 EST)
Consensus Forecast, Rate: 8.3%
Consensus Range, Rate: 8.3% to 8.4%
Forecasters expect no change at 8.3 percent.
US NFIB Small Business Optimism Index for October (Tue
0600 EST; Tue 1100 GMT)
Consensus Forecast, Index: 97.6
Consensus Range, Index: 97.0 to 98.4
Index expected down slightly at 97.6 in October from 97.9 in
September as business sentiment remains muted,
US CPI for October (Tue 0830 EST; Tue 1330 GMT)
Consensus Forecast, CPI - M/M: 0.3%
Consensus Range, CPI - M/M: 0.2% to 0.4%
Consensus Forecast, Ex-Food & Energy - M/M: 0.2%
Consensus Range, Ex-Food & Energy - M/M: 0.2% to 0.3%
Energy prices should lift CPI again. The consensus sees an
increase of 0.3 percent with 0.2 percent ex-food & energy for October.
Wednesday
Germany CPI for October (Wed 0800 CET; Wed 0700 GMT;
Wed 0200 EST)
Consensus Forecast, M/M: -0.2%
Consensus Range, M/M: -0.2% to -0.2%
Consensus Forecast, Y/Y: 2.8%
Consensus Range, Y/Y: 2.8% to 2.8%
Consensus Forecast, HICP - M/M: -0.1%
Consensus Range, HICP - M/M: -0.1% to -0.1%
Consensus Forecast, HICP - Y/Y: 2.8%
Consensus Range, HICP - Y/Y: 2.8% to 2.8%
Forecasters look for no revision in CPI in the final from
the flash with a decrease of 0.2 percent on the month and an increase of 2.8
percent on year for October.
Italy Industrial Production for September (Wed 1000
CET; Wed 0900 GMT; Wed 0400 EST)
Consensus Forecast, M/M: 0.9%
Consensus Range, M/M: -0.2% to 1.0%
Consensus Forecast, Y/Y: -0.7%
Consensus Range, Y/Y: -0.8% to 0.9%
The consensus sees industrial output up 0.9 percent on the
month in September and down 0.7 percent on year.
Thursday
Japan PPI for October (Thu 0830 JST; Wed 2330 GMT;
Wed 1830 EST)
Consensus Forecast, M/M: 0.2%
Consensus Range, M/M: 0.1% to 0.5%
Consensus Forecast, Y/Y: 6.5%
Consensus Range, Y/Y: 6.3% to 6.7%
UK Monthly GDP for September (Thu 0700 GMT;
Thu 0200 EST)
Consensus Forecast, M/M: 0.0%
Consensus Range, M/M: 0.0% to 0.2%
GDP growth expected flat on the month in September after a
negligible 0.1 percent in August.
Sweden CPI for October (Thu 0800 CET; Thu 0700 GMT;
Thu 0200 EST)
Consensus Forecast, Y/Y: 0.9%
Consensus Range, Y/Y: 0.9% to 0.9%
CPI expected up 0.9 percent on year in the October final,
unrevised from the October flash, down from 1.1 percent in September.
UK GDP for Third Quarter (Thu 0700 GMT; Thu 0200 EST)
Consensus Forecast, M/M: 0.7%
Consensus Range, M/M: 0.4% to 0.7%
Consensus Forecast, Y/Y: 1.9%
Consensus Range, Y/Y: 1.7% to 1.9%
A 0.7 percent gain is the call for Q3 from Q2.
UK Industrial Production for September (Thu 0700 GMT;
Thu 0200 EST)
Consensus Forecast, Industrial Production - M/M: -0.4%
Consensus Range, Industrial Production - M/M: -0.5%
to -0.3%
Consensus Forecast, Industrial Production - Y/Y: 1.7%
Consensus Range, Industrial Production - Y/Y: 0.4% to
2.9%
Consensus Forecast, Manufacturing Output - M/M: -0.5%
Consensus Range, Manufacturing Output - M/M: -0.5% to
-0.3%
Consensus Forecast, Manufacturing Output - Y/Y: 3.1%
Consensus Range, Manufacturing Output - Y/Y: 2.3% to 3.8%
Industrial output seen retreating by 0.4 percent on month
and up 1.7 percent on year in September after gains of 0.8 percent and 1.6
percent, respectively, in August.
UK Merchandise Trade for September (Thu 0700 GMT; Thu
0200 EST)
Consensus Forecast, Balance: -18.5 B
Consensus Range, Balance: -19.2 B to -18.5 B
The trade deficit expected barely wider at 18.3 billion
from 18.01 billion in August.
India CPI for October (Thu 1600 IST; Thu 1030 GMT;
Thu 0530 EST)
Consensus Forecast, Y/Y: 6.0%
Consensus Range, Y/Y: 6.0% to 6.2%
Energy prices expected to lift CPI to a 6.0 percent rate in
October from 5.54 percent in September.
US Jobless Claims for Week of November 07 (Thu 0830 EST;
Thu 1330 GMT)
Consensus Forecast, Initial Claims - Level: 195K
Consensus Range, Initial Claims - Level: 190K to 200K
Claims hovering in recent range, expected at 195K versus
189K last week.
US Existing Home Sales for October (Thu 1000 EST; Thu
1500 GMT)
Consensus Forecast, Annual Rate: 3.87 M
Consensus Range, Annual Rate: 3.70 M to 4.00 M
Rising mortgage rates expected to dampen sales to 3.87
million unit rate in October from 3.99 million in September.
Friday
France CPI for October (Fri 0845 CET; Fri 0745 GMT;
Fri 0245 EST)
Consensus Forecast, M/M: 0.4%
Consensus Range, M/M: 0.4% to 0.4%
Consensus Forecast, Y/Y: 3.4%
Consensus Range, Y/Y: 3.1% to 3.8%
Consensus Forecast, HICP - M/M: 0.4%
Consensus Range, HICP - M/M: 0.4% to 0.4%
Consensus Forecast, HICP - Y/Y: 3.8%
Consensus Range, HICP - Y/Y: 3.8% to 3.8%
The consensus sees no revision in the final from the flash
with CPI up 0.4 percent M/M and 3.4 percent Y/Y.
Eurozone GDP Flash for Third Quarter (Fri 1100 CET;
Fri 1000 GMT; Fri 0500 EST)
Consensus Forecast, Q/Q: 0.4%
Consensus Range, Q/Q: 0.4% to 0.4%
Consensus Forecast, Y/Y: 1.3%
Consensus Range, Y/Y: 1.3% to 1.3%
GDP expected up 0.4 percent on quarter and 1.3 percent on
year for Q3.
US PPI-Final Demand for October (Fri 0830 EST; Fri 1330
GMT)
Consensus Forecast, PPI-FD - M/M: 0.4%
Consensus Range, PPI-FD - M/M: 0.1% to 0.5%
Consensus Forecast, PPI - Y/Y: 6.6%
Consensus Range, PPI - Y/Y: 6.1% to 6.8%
Consensus Forecast, Ex-Food & Energy - M/M: 0.3%
Consensus Range, Ex-Food & Energy - M/M: 0.2% to 0.5%
Consensus Forecast, Ex-Food & Energy - Y/Y: 5.0%
Consensus Range, Ex-Food & Energy - Y/Y: 4.7% to 5.0%
Another month of big increases is the call for October with
PPI up 0.4 percent on month and 6.6 percent on year after gains of 1.3 percent
on month and 6.2 percent on year on September.
Canada Manufacturing Sales for September (Fri 0830
EST; Fri 1330 GMT)
Consensus Forecast, M/M: 0.1%
Consensus Range, M/M: -0.3% to 0.5%
Forecasters expect an increase of 0.1 percent on the month,
in line with the Statistics Canada advance estimate for September.
|