|
The Week Ahead: Highlights
Asia-Pacific Preview
Australia Jobs Report Key to Next RBA Rate Decision
By Brian Jackson, Econoday Economist
Australian labour data will be the highlight of the
Asia-Pacific data calendar in the week ahead. Temporary hiring for the national
census held in August will likely have some impact on the figures. At their
most recent policy meeting in early August, officials at the Reserve Bank of
Australia judged that labour market conditions have eased by a little more
than expected in recent months, and said they expect further limited easing in
the near term. Consistent with that assessment, July data released after the
meeting showed a fall in employment and a small increase in the unemployment
rate. Next weeks data will shape officials assessment of the outlook ahead of
the next policy meeting the following week.
Singapore inflation data may also influence the assessment
of officials at the Monetary Authority of Singapore ahead of their next policy
review in October. Officials tightened their exchange-rate policy at the last
meeting in July, noting that external price pressures are expected to persist
and pass through more broadly to domestic consumer prices in the period ahead.
Core inflation rose from 1.6 percent in June to 2.0 percent in July, and any
sign next week that price pressures are building may be enough to prompt
further policy tightening next month. Hong Kong will also report inflation
data.
The Peoples Bank of China will conduct its monthly review
of loan prime rates in the week ahead. These rates have been on hold since last
May. Officials provided little guidance on the policy outlook when monthly
activity data were published this week but characterised the data as showing
that the economy was generally stable.
Hong Kong and Thailand will report monthly trade data in the
week ahead. Hong Kong reported year-over-year export growth of 50.7 percent in
July, while Thailands exports rose 36.7 percent on the year. Trade data
already published elsewhere in the region have generally shown continued
strength in AI-related demand, outweighing the impact of disrupted access to
the Strait of Hormuz. Taiwanese industrial production data will also likely
remain supported by strong tech demand, while the flash PMI for India will give
an early indication of conditions in September.
US Preview
US Gasoline Prices in Focus as Mideast Supply Disruption
Continues
By Theresa Sheehan, Econoday Economist
Although the September 21 week includes some useful data
about recent conditions in the manufacturing and service sectors, the economic
data will feel out of date with the FOMC decision on September 16 to lift the
fed funds target rate range 25 basis points to 3.75 to 4.00 percent and the
volatility in energy prices as hostilities in the Middle East interfere with
oil supplies.
Businesses and consumers are going to be watching motor fuel
prices with an eye to the bottom line for operations and household budgets.
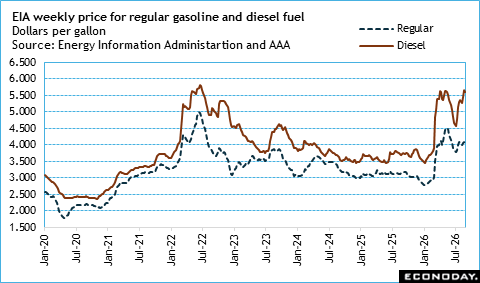
Prices for regular gasoline are below their record highs (according to AAA
$5.0165 per gallon on June 14, 2022) but high enough to affect consumer
purchasing power for non-discretionary spending. Businesses that require diesel
to power machinery and motor vehicles are facing record high prices (AAA
$6.3956 as of September 17, 2026) and approaching twice what they were paying a
year ago. These are not costs which can be easily absorbed and which will
result in higher prices to customers. Few passenger vehicles are diesel
engines, but transportation by train, bus, and truck will be negatively
impacted. Moreover, prices are going up at a time of year when they typically
decline when fuel refineries revert to winter formulations. It is also the time
of year when demand for heating oil starts to rise.
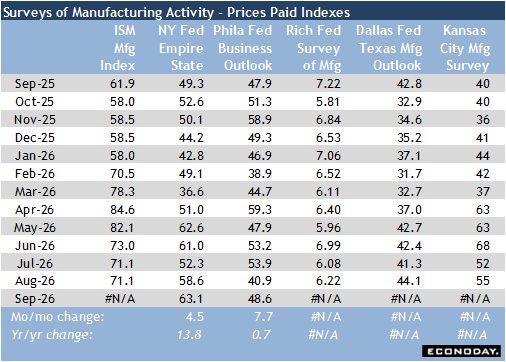
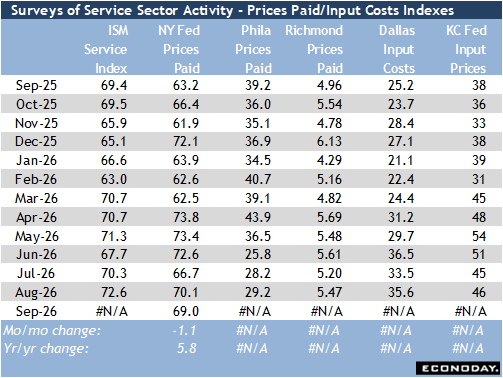
The September surveys for the factory and service sectors
compiled by five Fed district banks are one place to see if costs are rising
for businesses. Although surveys were taken early in the month, the September
data will broadly reflect the price pressures that were already present and
hint that more is to come given the upward trajectory of energy costs.
The September manufacturing surveys for New York and
Philadelphia have been released. This coming week will provide more
information. The Richmond Feds surveys for manufacturing and services are set
for 10:00 ET on Tuesday, along with the Chicago Feds indexes for manufacturing
and services. The Philadelphia Fed survey of non-manufacturing will be on
Tuesday at 8:30 ET. The Kansas City Fed will release its surveys of
manufacturing and services at 11:00 ET on Thursday and Friday, respectively.
The Dallas Fed surveys of manufacturing and services will not be reported until
10:30 ET on Monday and Tuesday, September 28 and 29, respectively.
Fed policymakers will be watching all the data related to
prices and inflation expectations to assess the risks to price stability and
the US economy in the weeks leading up to the October 27-28 FOMC meeting.
.
The Week Ahead: Econoday Consensus Forecasts
Monday
US Chicago Fed National Activity Index for August (Mon
0830 EDT; Mon 1230 GMT)
Consensus Forecast, Index: -0.08
Consensus Range, Index: -0.8 to 0.2
Index seen marginally negative at minus 0.08 in August.
Tuesday
Eurozone EC Consumer Confidence Flash for September (Tue
1600 CEST; Tue 1400 GMT; Tue 1000 EDT)
Consensus Forecast, Index: -16.8
Consensus Range, Index: -17.0 to -16.5
Sentiment is losing ground in the Eurozone owing to rising
energy costs. The consumer confidence index is expected at minus 16.8 for
September versus minus 15.5 in August.
US Richmond Fed Manufacturing Index for September (Tue
1000 EDT; Tue 1400 GMT)
Consensus Forecast, Index: -1
Consensus Range, Index: -2 to 2
Wednesday
Singapore CPI for August (Wed 1300 SGT; Wed 0500 GMT;
Wed 0100 EDT)
Consensus Forecast, Y/Y: 2.3%
Consensus Range, Y/Y: 2.2% to 2.4%
The consensus looks for CPI up 2.3 percent on year in
August, up only marginally from 2.2 percent in July.
France PMI Composite Flash for September (Wed 0915 CEST;
Wed 0715 GMT; Wed 0315 EDT)
Consensus Forecast, Manufacturing Index: 51.0
Consensus Range, Manufacturing Index: 50.5 to 51.2
Consensus Forecast, Services Index: 48.8
Consensus Range, Services Index: 47.8 to 49.1
The manufacturing index is seen almost unchanged at 51.0 in
the September flash versus 51.1 in the August final. Services expected at 48.8
versus 48.0 in the August final, suggesting ongoing slow contraction in
services business activity while manufacturing grows slowly.
Germany PMI Composite Flash for September (Wed 0930
CEST; Wed 0730 GMT; Wed 0330 EDT)
Consensus Forecast, Composite Index: 51.8
Consensus Range, Composite Index: 50.5 to 52.5
Consensus Forecast, Manufacturing Index: 54.3
Consensus Range, Manufacturing Index: 53.0 to 55.0
Consensus Forecast, Services Index: 50.1
Consensus Range, Services Index: 49.6 to 50.5
Slow expansion expected to continue in September with the
composite index unchanged at 51.8 from 51.8 in the August final.
Eurozone PMI Composite Flash for September (Wed 1000
CEST; Wed 0800 GMT; Wed 0400 EDT)
Consensus Forecast, Composite Index: 51.6
Consensus Range, Composite Index: 51.0 to 52.5
Consensus Forecast, Manufacturing Index: 52.7
Consensus Range, Manufacturing Index: 51.8 to 53.0
Consensus Forecast, Services Index: 51.4
Consensus Range, Services Index: 51.0 to 52.0
The consensus sees the composite flash for September at
51.6, close to the 52.0 final August index. That suggests ongoing slow
expansion.
UK PMI Composite Flash for September (Wed 0930 BST;
Wed 0830 GMT; Wed 0430 EDT)
Consensus Forecast, Composite Index: 52.2
Consensus Range, Composite Index: 52.0 to 52.3
Consensus Forecast, Manufacturing Index: 51.6
Consensus Range, Manufacturing Index: 51.5 to 51.8
Consensus Forecast, Services Index: 52.2
Consensus Range, Services Index: 52.0 to 52.4
The consensus forecast sees the UK composite flash at 52.2
in September, off from 52.5 in the August final.
US PMI Composite Flash for September (Wed 0945 EDT; Wed
1345 GMT)
Consensus Forecast, Manufacturing Index: 53.8
Consensus Range, Manufacturing Index: 53.0 to 54.7
Consensus Forecast, Services Index: 56.0
Consensus Range, Services Index: 53.7 to 56.4
Business activity seen expanding at about the same pace in
the first part of September with the manufacturing flash at 53.8 versus 53.9 in
the August final, and with services at 56.0 in September versus 56.5 in the
August final.
Thursday
Australia Labour Force Survey for August (Thu 1130
AEST; Thu 0130 GMT; Thu 2130 EDT)
Consensus Forecast, Employment - M/M: 20K
Consensus Range, Employment - M/M: 10K to 47K
Consensus Forecast, Unemployment Rate: 4.5%
Consensus Range, Unemployment Rate: 4.4% to 4.5%
Employment expected up 20K after falling 16K in July.
Jobless rate expected steady at 4.5%.
Norway Norges Bank Rate Decision (Thu 0800 CEST; Thu
0600 GMT; Thu 0200 EDT)
Consensus Forecast, Change: 25 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Level: 4.50%
Consensus Range, Level: 4.25% to 4.50%
Inflation pressures expected to prompt a 25 bp rate move, in
line with the ECB and the Fed.
Switzerland SNB Monetary Policy Assessment for September (Thu
0930 CEST; Thu 0730 GMT; Thu 0330 EDT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 0 bp
Consensus Forecast, Level: 0.0%
Consensus Range, Level: 0.0% to 0.0%
Growth may have picked up lately but inflation has not. That
lets the SNB keep rates where they are. The Swiss francs recent decline also
takes pressure off the SNB to intervene to keep the currency from rising, as it
tends to do.
Sweden Riksbank Rate Decision for September (Thu 0930
CEST; Thu 0730 GMT; Thu 0330 EDT)
Consensus Forecast, Change: 0 bp
Consensus Range, Change: 0 bp to 25 bp
Consensus Forecast, Level: 1.75%
Consensus Range, Level: 1.75% to 2.00%
The consensus looks for no rate move this week with a
hawkish bias and a 25 basis point rate hike coming later in the year, most
likely in November. The August inflation report came in on the soft side which
gives the Riksbank a breathing space even as energy costs keep inflation
pressure rising.
Germany Ifo Survey for September (Thu 1000 CEST; Thu
0800 GMT; Thu 0400 EDT)
Consensus Forecast, Business Climate: 89.0
Consensus Range, Business Climate: 87.0 to 89.3
Consensus Forecast, Current Conditions: 89.2
Consensus Range, Current Conditions: 87.0 to 89.5
Consensus Forecast, Business Expectations: 89.0
Consensus Range, Business Expectations: 87.5 to 89.2
Business climate index expected to improve slightly to 89.0
in September from 88.8 in August.
Canada Retail Sales for July (Thu 0830 EDT; Thu 1230
GMT)
Consensus Forecast, M/M: -0.8%
Consensus Range, M/M: -0.8% to -0.7%
The Statistics Canada advance retail indicator looks for
sales down 0.8 percent in July from June and forecasters agree.
US Jobless Claims for Week of September 19 (Thu 0830
EDT; Thu 1230 GMT)
Consensus Forecast, Initial Claims - Level: 204K
Consensus Range, Initial Claims - Level: 200K to 208K
The consensus expects claims to rebound from the low 196K
last week to 204K in the latest week.
US New Home Sales for August (Thu 1000 EDT; Thu 1400
GMT)
Consensus Forecast, Annual Rate: 618K
Consensus Range, Annual Rate: 600K to 640K
Sales expected to recover to a 618K rate in August from 607K
in July.
US Kansas City Fed Manufacturing Index for September (Thu
1100 EDT; Thu 1500 GMT)
Consensus Forecast, Level: 8
Consensus Range, Level: 5 to 9
Manufacturing index expected at 8 in September versus 10 in
August.
Friday
Germany GfK Consumer Climate for October (Fri 0800 CEST;
Fri 0600 GMT; Fri 0200 EDT)
Consensus Forecast, Index: -27.0
Consensus Range, Index: -27.6 to -26.0
Consumer sentiment expected to decline to minus 27.0 in
October from minus 26.6 in September.
Eurozone M3 Money Supply for August (Fri 1000 CEST; Fri
0800 GMT; Fri 0400 EDT)
Consensus Forecast, Y/Y - 3-Month Moving Average: 3.5%
Consensus Range, Y/Y - 3-Month Moving Average: 3.4%
to 3.5%
Money growth expected at 3.5 percent annual rate in August,
up from 3.2 percent in July.
US Durable Goods Orders for August (Fri 0830 EDT; Fri
1230 GMT)
Consensus Forecast, New Orders - M/M: -0.4%
Consensus Range, New Orders - M/M: -1.5% to 0.4%
Consensus Forecast, Ex-Transportation - M/M: 0.5%
Consensus Range, Ex-Transportation - M/M: 0.1% to
0.7%
Durables expected down 0.4 percent with ex-transportation
durables up 0.5 percent.
US Consumer Sentiment for September Final (Fri 1000
EDT; Fri 1400 GMT)
Consensus Forecast, Index: 47.8
Consensus Range, Index: 45.5 to 47.8
The consensus sees no revision in sentiment for the final
September report from 47.8 in the flash.
|